
A business credit report summarises a company’s financial and credit history, compiled by agencies such as Experian, Equifax and Creditsafe. They use data from legitimate sources like Companies House and the courts. To read one, focus on the key indicators: the credit score and recommended credit limit, any County Court Judgments (CCJs), payment performance, and the filed accounts. Safe Collections can support you if you are chasing a debt from the company you’re checking.
In this article, we’ll show you an example UK business credit report from Experian and show you how to interpret it.
Table of Contents
How to Get a Business Credit Report
If you’d like to get a business credit report (or check a business credit score), you can obtain one directly from credit reference agencies. You search for the company by name or Companies House registration number, pay a fee, and receive the report immediately online.
Safe Collections works with Experian and can offer 50% off business credit reports.
For free basic information, Companies House is publicly searchable and will show you filed accounts, director details, and registered charges. However, it does not provide a credit score, payment performance data, or CCJ information.
How Do I Check My Own Business Credit Score?
You can check your own business credit score through any of the main credit reference agencies in the same way you would check a client’s. Search for your company by name or registration number on their platform.
Most agencies also offer ongoing business credit monitoring services that track your score over time and alert you to changes. This is worth doing because your credit profile affects how suppliers and lenders perceive your business, and errors in your credit file can be disputed and corrected once identified.
If your score is lower than expected, the report will usually indicate which factors are dragging it down, giving you a starting point for addressing them.
Credit Reports Broken Down: How to Read Yours
Here’s a real company credit report that we obtained from Experian. Keep in mind that this is a standard report for a UK business, and reports for other countries will vary.
If you’re credit checking a customer who has not paid you, review our guide to recovering unpaid invoices along with this article.
No Cost. No Obligation.
100% Confidential.
Company Summary
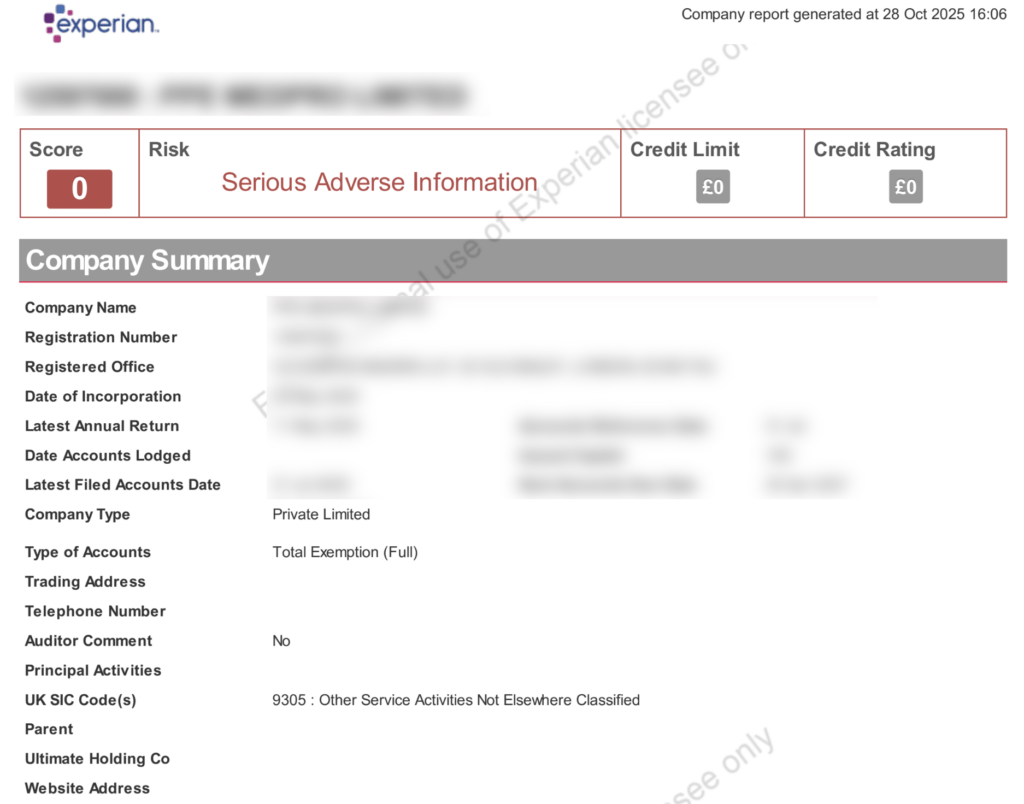
The first section in a standard business credit report is the Company Summary, which provides you with some information about the company’s incorporation, accounts filed, address, and contact details.
Credit Score
At the top of the report, you’ll see a credit score or rating. This provides a key at-a-glance summary of a business’ financial and credit history.
Typically, a credit score will rate a company out of 100 on the likelihood of it paying debts quickly and fairly, with 100 being a ‘perfect’ debtor. The score will usually be displayed graphically, often using a red, amber, green colour coding system.
Additional information provided may include:
- Limiting Factors: Details from the company’s credit history that have lowered the score. These may include serious adverse information such as details of CCJs and writs against the company.
- Risk summary: A short statement summarising the anticipated risk of non-payment in words.
- Risk comparison: Placing the company’s credit score in the context of default risks across that industry.
No credit score may be given in instances where there has been a bankruptcy associated with the business, or where there is insufficient information available.
Credit Limit
The credit report will usually recommend a maximum credit limit for a business, based on overall liabilities and financial performance.
This gives potential creditors an idea of a ‘safe’ level of business a partner should be able to pay for, and what would be overstretching them.
Company Summary
In this section of the credit report, you’ll want to review corporate information such as:
- Registered names
- Addresses
- Contact details
- How long the business has been operating
- Their Indentity History, such as alternative operating names and addresses. This provides a safeguard against businesses with a poor credit history changing their name.
Use this information to verify that your client is who they say they are. Also, check there is no association with other businesses with a poor credit history.
The report will also list details of holding and subsidiary companies, including linkages to any overseas operations, along with details of current and previous directors. This latter information is important to flag up any instances where company directors have filed for bankruptcy.
Accounts
Credit reports sometimes include details of business accounts going back up to five years. This again gives a picture of the financial health of a business, which is useful for weighing up the risks of supplying them.
Change History
Scrolling down the report, you’ll come to the Change History section. This is a timeline of events, including some routine entries (like the filing of accounts), plus more noteworthy changes, like credit scores being reduced.

If you see that the company has been placed into administration, that’s an obvious warning sign that you should avoid doing business with them.
But there are other patterns to look for, such as Credit Risk Score decreasing, Credit Risk Band changing for the worse, or accounts not being filed on time. That could indicate that the company is having financial issues. If you see patterns of decline, you can use that information to decide whether you want to supply them or not.
In some cases, you may find it easier to review score changes in a chart, which is provided further down in the report. We’ll explain that here later.
Mortgages
The mortgages section of a business credit report includes a Summary of Mortgages, Charges and Satisfactions, which is a list of debts the company has.
A charge means that security is being held against company assets. The lender can claim those if the business defaults on the loan. A satisfaction is a debt that has been fully repaid.
In this section, look for outstanding or partially satisfied loans and mortgages. This will give you an idea of the company’s debts.
Risk Summary
The Risk Summary is a concise summary of the credit report in plain English, which may make a recommendation on whether you should deal with them or not.
In some cases, like our example credit report, the summary is clear and direct.

Adverse Credit
This section shows any CCJs that have been issued against the company, and any administration orders.
Score History
The score history is a visual representation of Credit Score Changes and Credit Limit Changes over time. In our example credit report, the change is sudden and pronounced. In other reports, there may be a trend over time.

Payment Performance
The Payment Performance section will tell you whether a company pays its suppliers and creditors on time.
If the company has not paid its suppliers, you may see:
- Average days late
- Percentage paid on time (within 30, 60, or 61+ days)
- Trends in payment habits.
Financial Summary
The business credit report breaks down financial performance in a number of different sections, which are fairly self explanatory:
- Summary
- Profit And Loss
- Balance Sheets
- Cashflow
- Financial Notes
- Ratios
- Growth
- Industry Comparison
Use these sections to drill down into the financials and examine the company’s finances in different areas.
Company Structure
This final section of the report breaks down the company’s relationship with any other companies it’s associated with. It lists all Company Directors and Shareholders.
Frequently Asked Questions About Business Credit Reports
What is a Business Credit Report?
A business credit report is a document that summarises the financial and credit history of a company. It is compiled by a credit reference agency. In the UK, the main providers are Experian, Equifax, and Creditsafe.
It draws on data from Companies House, court records, and financial filings, and typically includes:
- Credit score
- Recommended credit limit
- Details of any County Court Judgments (CCJs)
- Payment performance data
- Summary of the company’s filed accounts and financial position.
What is a Business Credit Score?
A business credit score is a number that summarises a company’s creditworthiness at a glance. Experian, for example, scores businesses out of 100, with higher scores indicating lower credit risk.
As a general guide:
- 80–100: Low risk
- 50–79: Moderate risk
- Below 50: Higher risk
- No score: Insufficient data, or a negative entry associated with the business
The score is calculated from the data in the credit report, which includes:
- Payment history
- CCJs
- Filed accounts
- Director history
It changes over time as new information becomes available.
Different agencies use different scoring scales, so always check which system applies when comparing scores from different sources.
What is the Difference Between a Business’ Credit Report and Its Credit Score?
The credit score is a single number derived from the credit report. The report is the full document that sits behind that number, containing all the detailed data and history the score is calculated from.
Think of the score as the headline and the report as the full story.
The score tells you quickly whether a client is low, medium, or high risk. The report tells you why.
For most credit decisions, you need both: the score for a quick initial assessment, and the report to understand the detail before committing to significant credit terms.
What’s the Difference Between the UK Credit Reference Agencies: Experian, Equifax, and Creditsafe?
Business credit reports in the UK are produced by several different agencies, and while the information they draw on is broadly similar, the way they present it can differ.
- Experian is one of the most widely used agencies for business credit reports in the UK. Their reports include a credit score out of 100, a recommended credit limit, CCJ data, filed accounts, and payment performance history. The walk-through above uses an Experian report.
- Equifax provides similar information but uses a different scoring methodology. Their business credit scores run from 0 to 1,000, with higher scores indicating lower risk. They also include director history, which can be useful for identifying connections between companies.
- Creditsafe is widely used by credit control teams and is known for its payment performance data, which draws on a large network of trade payment references. If understanding how a business actually pays its suppliers (rather than its theoretical credit score) is your priority, Creditsafe’s payment data can be useful.
For most purposes, any of the three will provide enough information to make a decision.
How Often Should I Run Credit Checks on Clients?
At minimum, run a credit check before extending credit to any new client.
For existing clients on ongoing credit terms, an annual or bi-annual check is good practice.
For larger accounts or clients showing any change in payment behaviour, more frequent checks are advisable.
Credit monitoring services offered by the main agencies will alert you automatically when a client’s score changes, a CCJ is registered, or an insolvency event occurs.
What Do I Do If a Client Fails a Credit Check?
If a credit check raises concerns, you have several options depending on the severity of what you find.
You might require upfront payment rather than extending credit, reduce the credit limit you are willing to offer, ask for a personal guarantee from a director, or decline to take the client on at all.
If you are already supplying a client whose credit report has deteriorated, act quickly. Reducing your exposure, stopping supply until overdue invoices are paid, and seeking professional debt recovery advice early all improve your chances of recovering what you are owed.
If invoices are already overdue, contact Safe Collections for a free review of your situation. Our experienced advisors can help you assess the risk and decide on the best course of action.
How to Make Decisions Based on a Company Credit Report
When reading a company credit report, it’s important to read the whole document and take it as a sum of its parts. If a section is blank, it does not necessarily mean you are safe, since there may be red flags in other areas.
In addition, some of the information on the report will come from Companies House, which means it won’t be verified. The extra information on a credit report can be helpful. For example, reviewing the company’s credit score history is usually worthwhile when taking on any new client.
If you see conflicting information, or you’re already having issues getting paid, contact us for a free review of your situation. Our experienced debt advisors can help you to decide your next step.
